2 Basic Properties of Random Vectors
Let \(\underline {X}'=\begin {pmatrix} x_1, & x_2, & \cdots , & x_p\\ \end {pmatrix} \) be a random vector. Then
- 1.
- The cumulative distribution function (CDF) is the function \(F\) defined by \(F(\underline {X}')\) \begin {equation} \tag {1} F(\underline {X}^0)=Pr\big (\underline {X}'\leq \underline {X}^0\big ) = Pr\big (x_1\leq x_1^0, x_2\leq x_2^0, \ldots , x_p\leq x_p^0\big ) \end {equation}
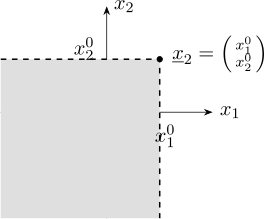
\[Pr(\underline {X}\leq x_2^0) = Pr(x_1\leq x_1^0, x_2\leq x^0_2)\]
There are two cases continuous and discrete distributions.
- (a)
- \(\displaystyle {F(\underline {X} = \int ^{\infty }_{-\infty }f(\underline {U})d\underline {U}}\qquad (2)\) where \(d\underline {U}=du_1\cdot du_2\cdot \cdots du_p\) \[\int ^{\underline {X}}_{-\infty } = \int ^{x_1}_{-\infty }\int ^{x_2}_{-\infty }\cdots \int ^{x_p}_{-\infty }\]
- (b)
- \(\displaystyle {\int ^{\infty }_{-\infty }f\big (\underline {U}\big )d\underline {U}=1}\)
A random vector \(\underline {X}\) is discrete if there exists a probability mass function (Pmf) \(f\big (\underline {U}\big )\) such that \[f\big (\underline {X}_j\big ) = \begin {cases} Pr\big (\underline {X}=\underline {X}_j & j=1,2,\ldots \\\\ 0, & \text {otherwise}\\ \end {cases} \]
2.1 Marginal and Conditional Distribution Functions
2.2 Independence
2.3 Population Moments
2.4 Conditional Moments
2.5 Correlation Matrix
2.6 Practice Problems
2.2 Independence
2.3 Population Moments
2.4 Conditional Moments
2.5 Correlation Matrix
2.6 Practice Problems
Questions on this section
Stuck on something here? Ask below and it stays attached to this topic.