8.2 The Poisson process
Definition 8.2.1. A function \(f\) is said to be \(o(h)\) if \[ \lim _{h\to 0}\frac {f(h)}{h} = 0 ; \] that is, for small \(h\), \(f(h)\) is small even in relation to \(h\). For example, \(f(h) = h^2\) is \(o(h)\), since \(h^2/h = h \to 0\), but \(f(h) = h\) is not.
Suppose that “events” occur at random time points, and let \(N(t)\) denote the number of events that occur in the time interval \([0, t]\).
Definition 8.2.2. The collection of random variables \(\{N(t) : t \ge 0\}\) is a Poisson process with rate \(\lambda > 0\) if
- (i)
- \(N(0) = 0\);
- (ii)
- the numbers of events that occur in disjoint time intervals are independent;
- (iii)
- the distribution of the number of events that occur in a time interval depends only on the length of that interval;
- (iv)
- \(P\bigl (N(h) = 1\bigr ) = \lambda h + o(h)\);
- (v)
- \(P\bigl (N(h) \ge 2\bigr ) = o(h)\).
Remark. Condition (i) says that the count starts at time zero. Condition (ii) says, for instance, that the numbers of events in the intervals \((t, t + s]\) and \((t + k, t + b]\), with \(s < k < b\), are independent, because the intervals do not overlap:
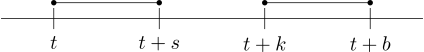
Conditions (iv) and (v) say that in a short interval of length \(h\) there is one event with probability about \(\lambda h\), and that two or more events are much less likely still. Together they give \[ P\bigl (N(h) = 0\bigr ) = 1 - P\bigl (N(h) = 1\bigr ) - P\bigl (N(h) \ge 2\bigr ) = 1 - \lambda h + o(h) . \]
Lemma 8.2.3. For a Poisson process with rate \(\lambda \), \(P\bigl (N(t) = 0\bigr ) = e^{-\lambda t}\).
Proof. Write \(P_0(t) = P\bigl (N(t) = 0\bigr )\). There are no events in \([0, t + h]\) exactly when there are none in \([0, t]\) and none in \((t, t + h]\). By conditions (ii) and (iii), \begin {align*} P_0(t + h) &= P\bigl (N(t) = 0,\ N(t + h) - N(t) = 0\bigr ) \\ &= P\bigl (N(t) = 0\bigr )\,P\bigl (N(t + h) - N(t) = 0\bigr ) \\ &= P_0(t)\,P\bigl (N(h) = 0\bigr ) = P_0(t)\bigl (1 - \lambda h + o(h)\bigr ) . \end {align*}
Hence \[ \frac {P_0(t + h) - P_0(t)}{h} = -\lambda P_0(t) + \frac {o(h)}{h} , \] and letting \(h \to 0\) gives \(P_0'(t) = -\lambda P_0(t)\), that is, \(P_0'(t)/P_0(t) = -\lambda \). Integrating, \[ \ln P_0(t) = -\lambda t + c , \qquad \text {so}\qquad P_0(t) = ke^{-\lambda t} , \quad k = e^c . \] Since \(P_0(0) = P\bigl (N(0) = 0\bigr ) = 1\), we have \(k = 1\), and \(P_0(t) = e^{-\lambda t}\). □
Let \(T_1\) be the time of the first event and, for \(n \ge 2\), let \(T_n\) be the time elapsed between the \((n - 1)\)th event and the \(n\)th event. The sequence \(\{T_n\}\) is called the sequence of inter-arrival times. For example, if \(T_1 = 4\) and \(T_2 = 12\), then the first event occurred at time \(4\) and the second at time \(16\).

Result 8.2.4. The inter-arrival times \(T_1, T_2, \dots \) of a Poisson process with rate \(\lambda \) are independent and identically distributed, each exponential with mean \(1/\lambda \).
Proof. The first event happens after time \(t\) exactly when there is no event in \([0, t]\), so by Lemma 8.2.3 \[ P(T_1 > t) = P\bigl (N(t) = 0\bigr ) = e^{-\lambda t} , \qquad \text {that is,}\qquad P(T_1 \le t) = 1 - e^{-\lambda t} , \] and \(T_1\) is exponential with mean \(1/\lambda \). For \(T_2\), condition on \(T_1\). By conditions (ii) and (iii), \begin {align*} P(T_2 > s \mid T_1 = t) &= P\bigl (\text {no event in the interval } (t, t + s] \mid T_1 = t\bigr ) \\ &= P\bigl (N(s) = 0\bigr ) = e^{-\lambda s} . \end {align*}
This does not depend on \(t\), so \(T_2\) is independent of \(T_1\), and \(T_2\) is exponential with mean \(1/\lambda \). Repeating the argument, conditioning on \(T_1, \dots , T_{n-1}\), gives the result for every \(T_n\). □
Denote by \(S_n\) the time of the \(n\)th event, the waiting time until the \(n\)th event occurs: \[ S_n = \sum _{i=1}^nT_i . \] By Result 8.2.4, \(S_n\) is a sum of \(n\) independent exponential variables with mean \(1/\lambda \), so it has the gamma distribution with shape \(n\) and rate \(\lambda \): \[ f_{S_n}(x) = \frac {\lambda ^nx^{n-1}e^{-\lambda x}}{\Gamma (n)} = \frac {(\lambda x)^{n-1}\lambda e^{-\lambda x}}{(n - 1)!} , \qquad x > 0 . \] We use this to find the distribution of \(N(t)\).
Theorem 8.2.5. For a Poisson process with rate \(\lambda \), the number \(N(t)\) of events in \([0, t]\) has the Poisson distribution with mean \(\lambda t\): \[ P\bigl (N(t) = n\bigr ) = \frac {(\lambda t)^ne^{-\lambda t}}{n!} , \qquad n = 0, 1, 2, \dots \]
Proof. The case \(n = 0\) is Lemma 8.2.3, so let \(n \ge 1\). The \(n\)th event occurs at or before time \(t\) if and only if at least \(n\) events occur in \([0, t]\): \[ N(t) \ge n \iff S_n \le t . \] Therefore \begin {align*} P\bigl (N(t) = n\bigr ) &= P\bigl (N(t) \ge n\bigr ) - P\bigl (N(t) \ge n + 1\bigr ) \\ &= P(S_n \le t) - P(S_{n+1} \le t) \\ &= \int _0^t\frac {(\lambda x)^{n-1}\lambda e^{-\lambda x}}{(n - 1)!}\,dx - \int _0^t\frac {(\lambda x)^n\lambda e^{-\lambda x}}{n!}\,dx . \end {align*}
Integrate the second integral by parts, with \(u = (\lambda x)^n/n!\) and \(dv = \lambda e^{-\lambda x}\,dx\), so that \(du = (\lambda x)^{n-1}\lambda \,dx/(n - 1)!\) and \(v = -e^{-\lambda x}\): \begin {align*} \int _0^t\frac {(\lambda x)^n\lambda e^{-\lambda x}}{n!}\,dx &= \Bigl [-\frac {(\lambda x)^n}{n!}e^{-\lambda x}\Bigr ]_0^t + \int _0^t\frac {(\lambda x)^{n-1}\lambda e^{-\lambda x}}{(n - 1)!}\,dx \\ &= -\frac {(\lambda t)^ne^{-\lambda t}}{n!} + \int _0^t\frac {(\lambda x)^{n-1}\lambda e^{-\lambda x}}{(n - 1)!}\,dx . \end {align*}
Substituting, the two remaining integrals cancel, and \[ P\bigl (N(t) = n\bigr ) = \frac {(\lambda t)^ne^{-\lambda t}}{n!} . \] □
Example 8.2.6. An insurance company runs a \(24\)-hour hotline, and claims are reported according to a Poisson process with rate \(4\) claims per day. Find
- (i)
- the probability that more than \(2\) claims are reported on a given day;
- (ii)
- the probability that the time until the next reported claim is more than an hour.
Solution. (i) With \(t = 1\) day, \(N(1)\) is Poisson with mean \(4\), so \begin {align*} P\bigl (N(1) > 2\bigr ) &= 1 - P\bigl (N(1) \le 2\bigr ) = 1 - \sum _{k=0}^2\frac {4^ke^{-4}}{k!} \\ &= 1 - e^{-4}\Bigl (1 + 4 + \frac {4^2}{2}\Bigr ) = 1 - 13e^{-4} = 0.7619 . \end {align*}
(ii) Measured in hours, the rate is \(\lambda = 4/24 = 1/6\) claims per hour. By Result 8.2.4, the time \(T\) until the next claim is exponential with rate \(1/6\), that is, with mean \(E(T) = 6\) hours. Hence \[ P(T > 1) = e^{-\lambda \cdot 1} = e^{-1/6} = 0.8465 . \]
Questions on this section
Stuck on something here? Ask below and it stays attached to this topic.